Case study · Consumer fintech
Credit card matchmaker
A credit card matchmaker for the UAE. Tell it how you spend, get your top three cards back, on WhatsApp.
- Client
- Founder-led consumer fintech startup
- Product
- Card comparison and recommendation platform
- Sector
- Consumer fintech
- Region
- United Arab Emirates
At a glance
What shipped
Between a visitor and their shortlist. No account, no long form.
Ranked by estimated net annual savings after fees, from how the visitor says they spend.
Results go to the channel UAE residents already default to.
The capture flow has already been through a full iteration since launch.
The brief
Trustworthy first. Clever second.
The UAE's credit card market is dense and easy to get wrong. Dozens of cards across more than a dozen banks, each with its own cashback categories, minimum salary thresholds and fine print that changes often. Most residents, and especially the country's large expat population, either take whatever card their salary-transfer bank offers or spend hours cross-referencing bank websites that were never designed to be compared.
The founder wanted one place where someone could describe how they actually spend and get back a short, honest answer, without wading through terms and conditions or feeling that the recommendation was an ad in disguise. And he needed it in front of real users fast, rather than spending a year building before learning whether the idea worked.
Describe how you spend. Get a short, honest answer. No ad in disguise.
Why the category is hard
Three reasons comparison sites lose trust
The market is dense
Dozens of cards across more than a dozen banks, each with its own categories and eligibility rules. Nobody compares them by hand for long.
The fine print moves
Cashback rates, fees, salary thresholds and promotions change often. A comparison is only as honest as its most recently updated row.
Defaults win
Without a better answer, people take the card their salary-transfer bank hands them, whether or not it suits how they spend.
The user side
Spending in. Shortlist out.
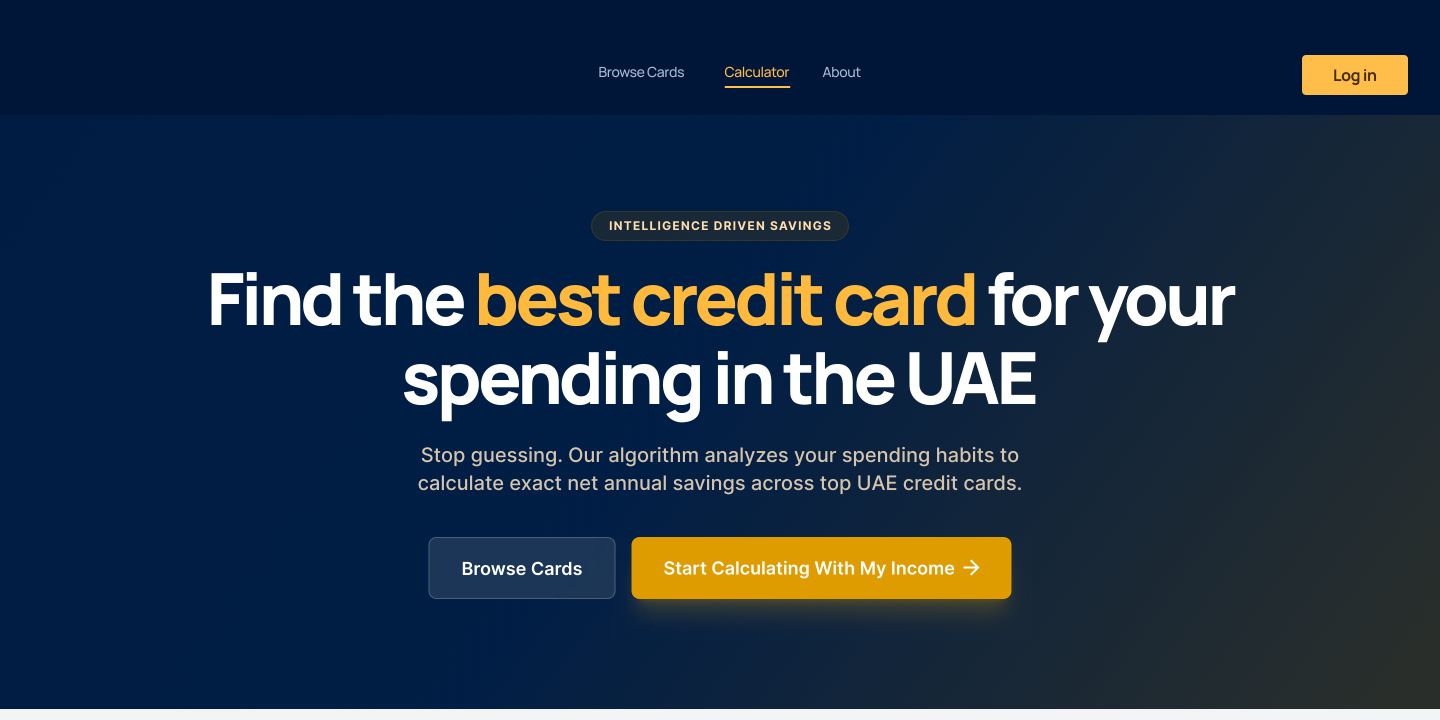
A visitor lands on the site and moves through a short, calculator-style flow: monthly income and spending by category in, a shortlist of matching cards out, ranked by estimated net annual savings after fees.
There is no login anywhere in this path. Every screen was designed around the two questions a first-time visitor actually has: does this apply to me, and how do I get it without handing my email to ten different banks.
- Income and spending sliders across groceries, dining, travel, fuel, shopping, utilities and car rental
- A top three with estimated savings, annual fee, minimum income and the categories that earn
- A plain-language line on every card: because you spend heavily on dining and travel
The calculator
One interaction does the heavy lifting
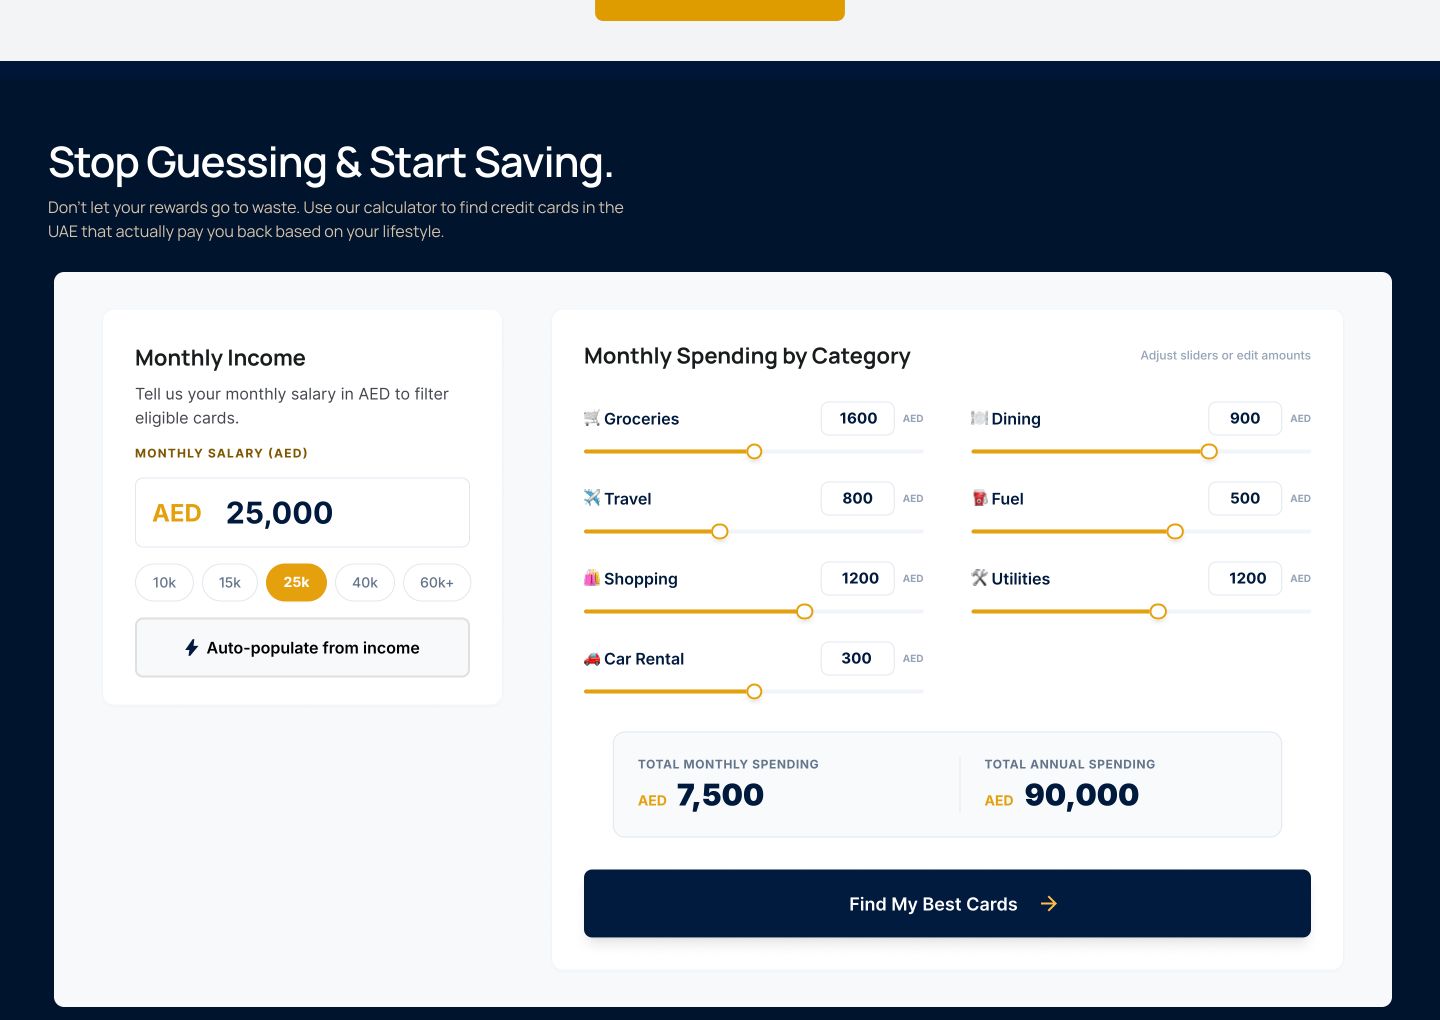
The calculator: monthly income and spend by category, then Find My Best Cards.
After launch
“Apply Now” became “Send to my WhatsApp”
The first version ended in an Apply Now button. The live version ends with Get my top 3 cards: a lightweight capture step that sends the results straight to WhatsApp, the channel UAE residents already default to, instead of an email they may never open. It shipped as an iteration on the live product, not as a second project.
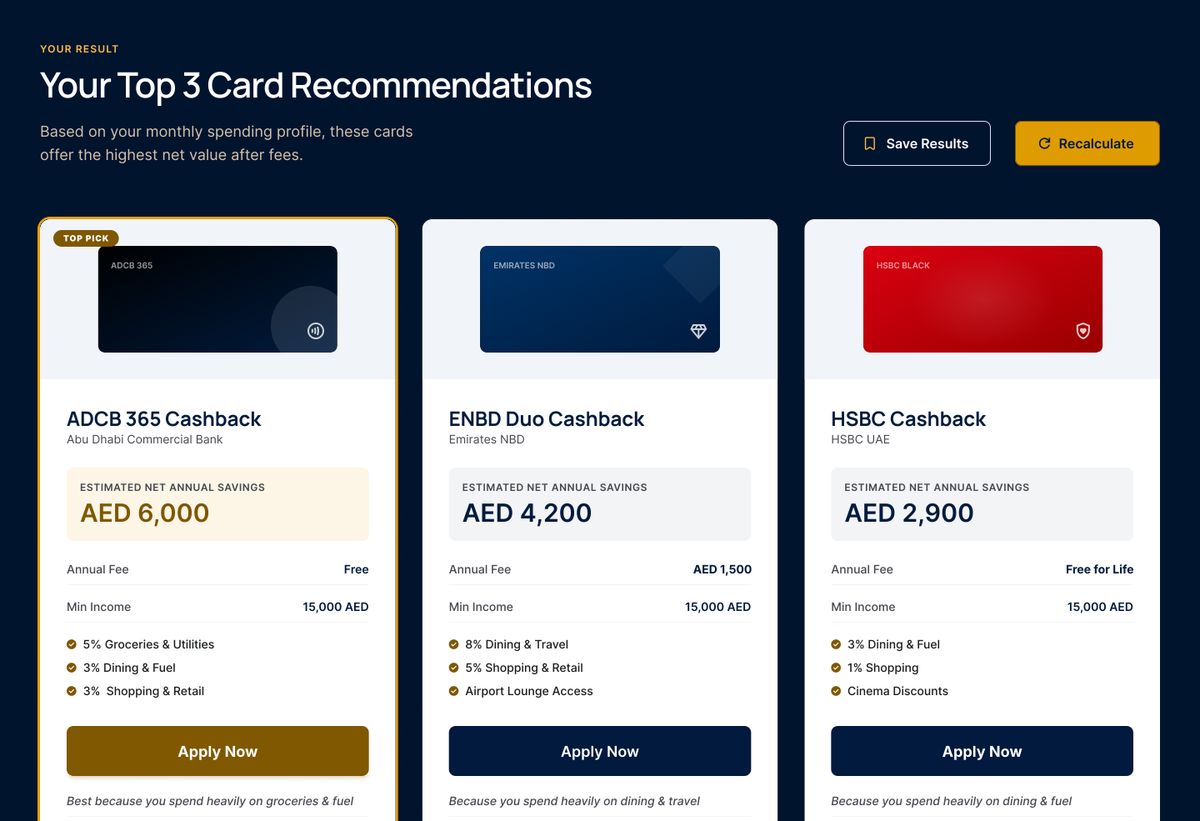
Launch version: each recommendation ends in Apply Now.
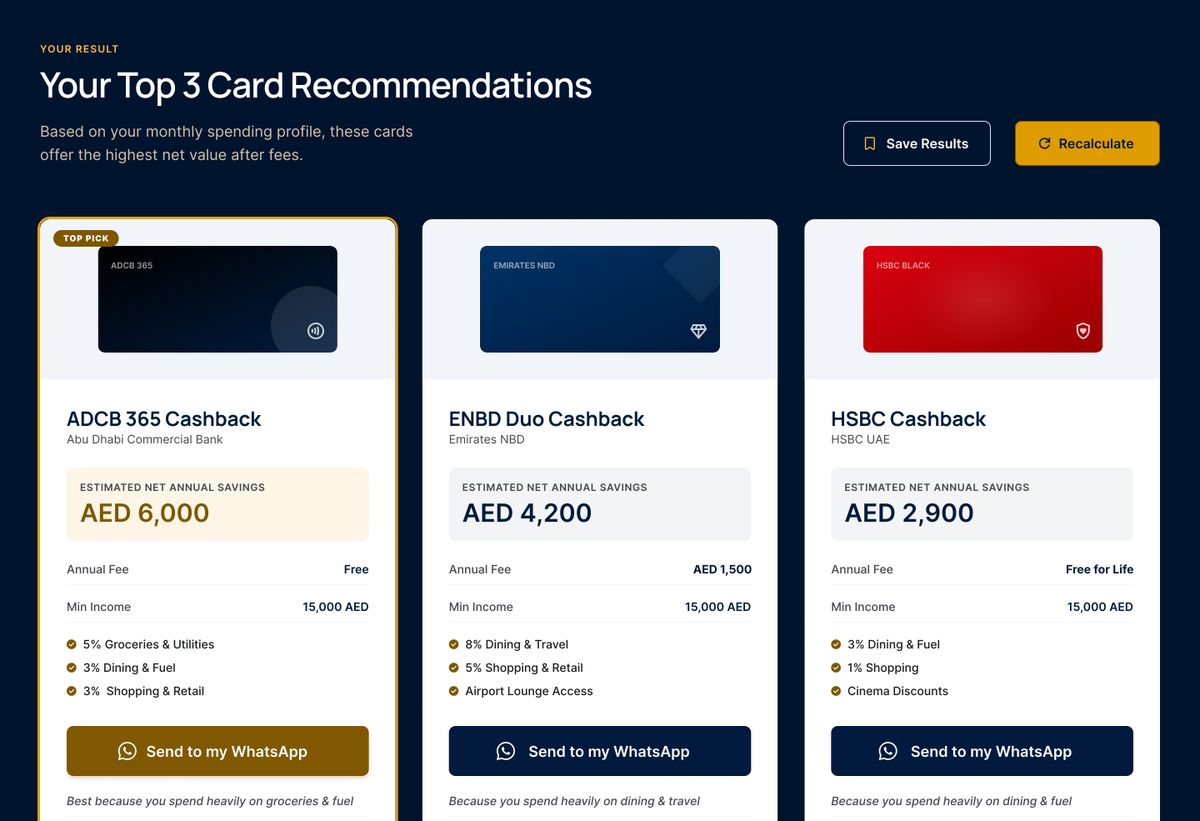
Live version: results go to the visitor's WhatsApp.
The admin side
A comparison tool is only as honest as its last updated row
Behind the calculator sits a content and rate management system, not a static spreadsheet. Two parts of it do the heavy lifting.
Card and bank rate management is where the team keeps every bank's cashback categories, fees, minimum salary thresholds and promotional offers current as banks change them. This is the part that protects the product's credibility.
A content management layer handles the buyer-question and comparison pages the site publishes, so the team can add or edit an answer page without touching code. Together they let the product keep pace with a market that changes its terms more often than most comparison sites are built to handle.
Inside the admin
Rates, cashback and every change, in one place
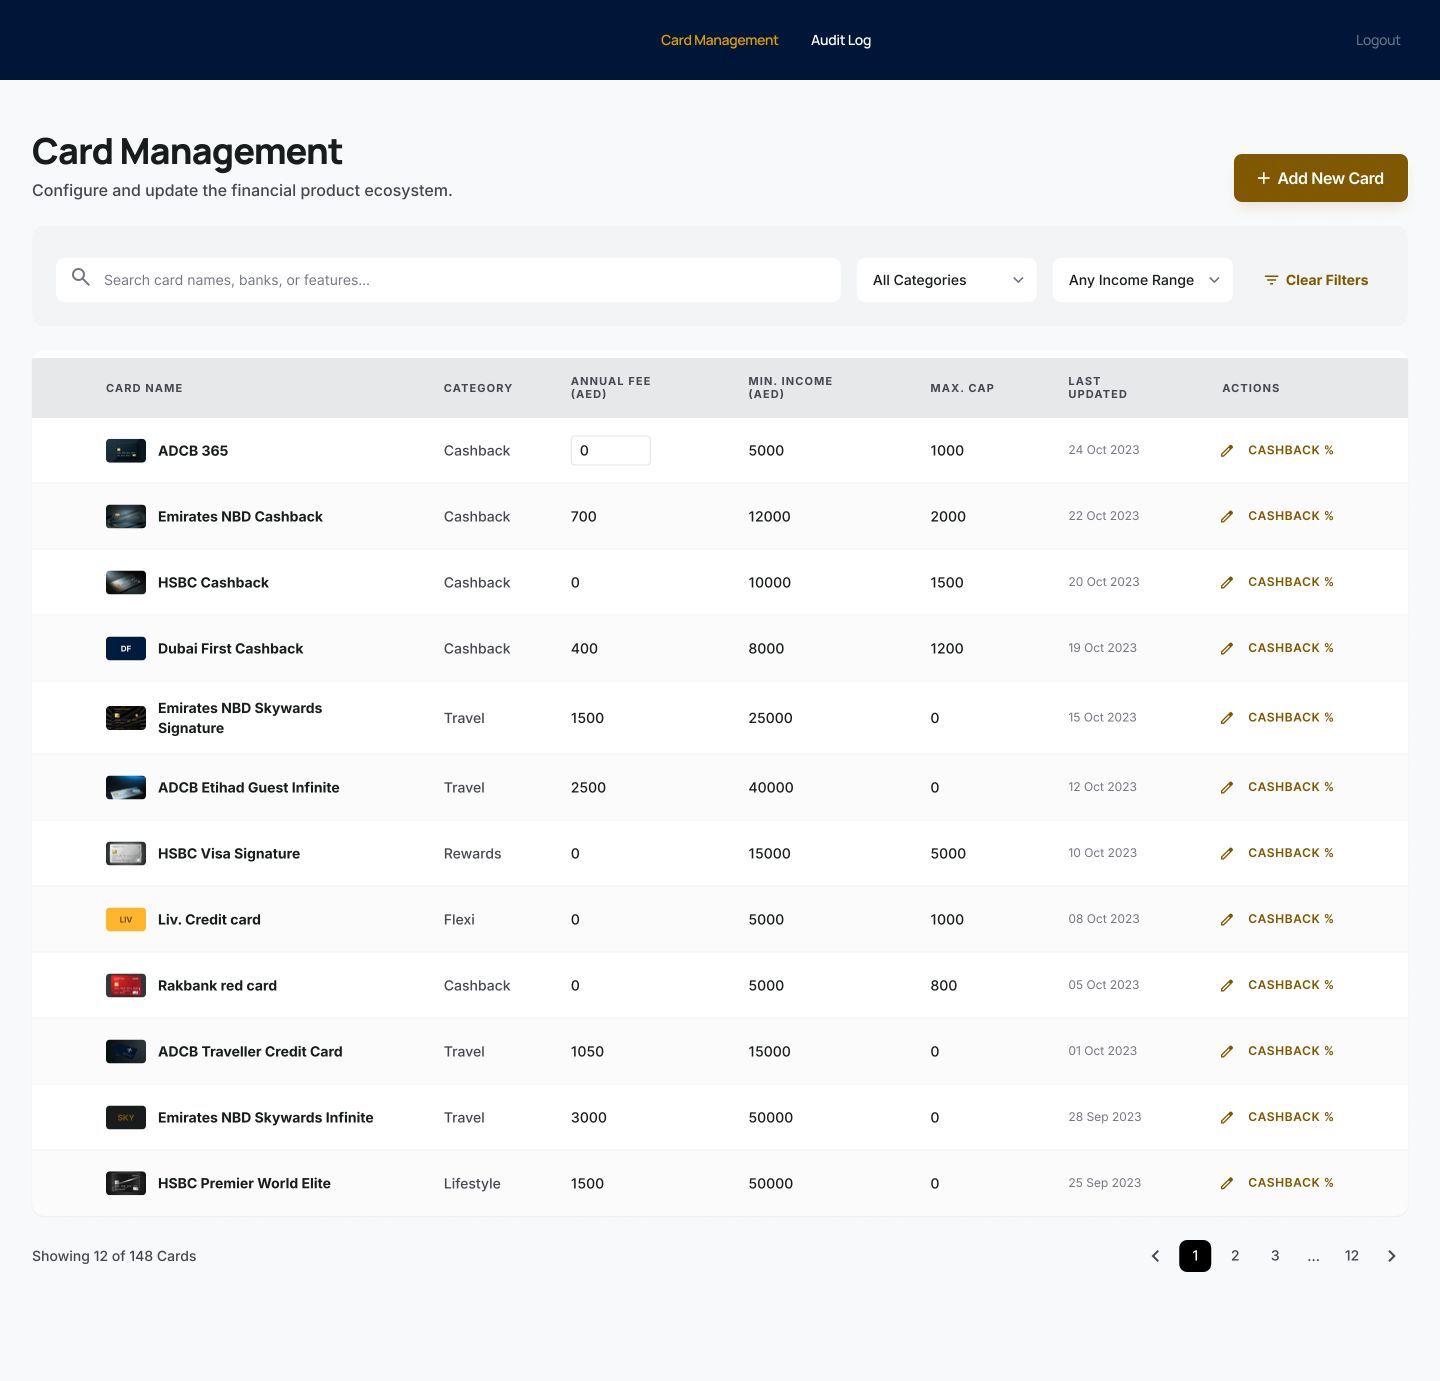
Card management: search, filter and edit every card's fee, income threshold and cap.
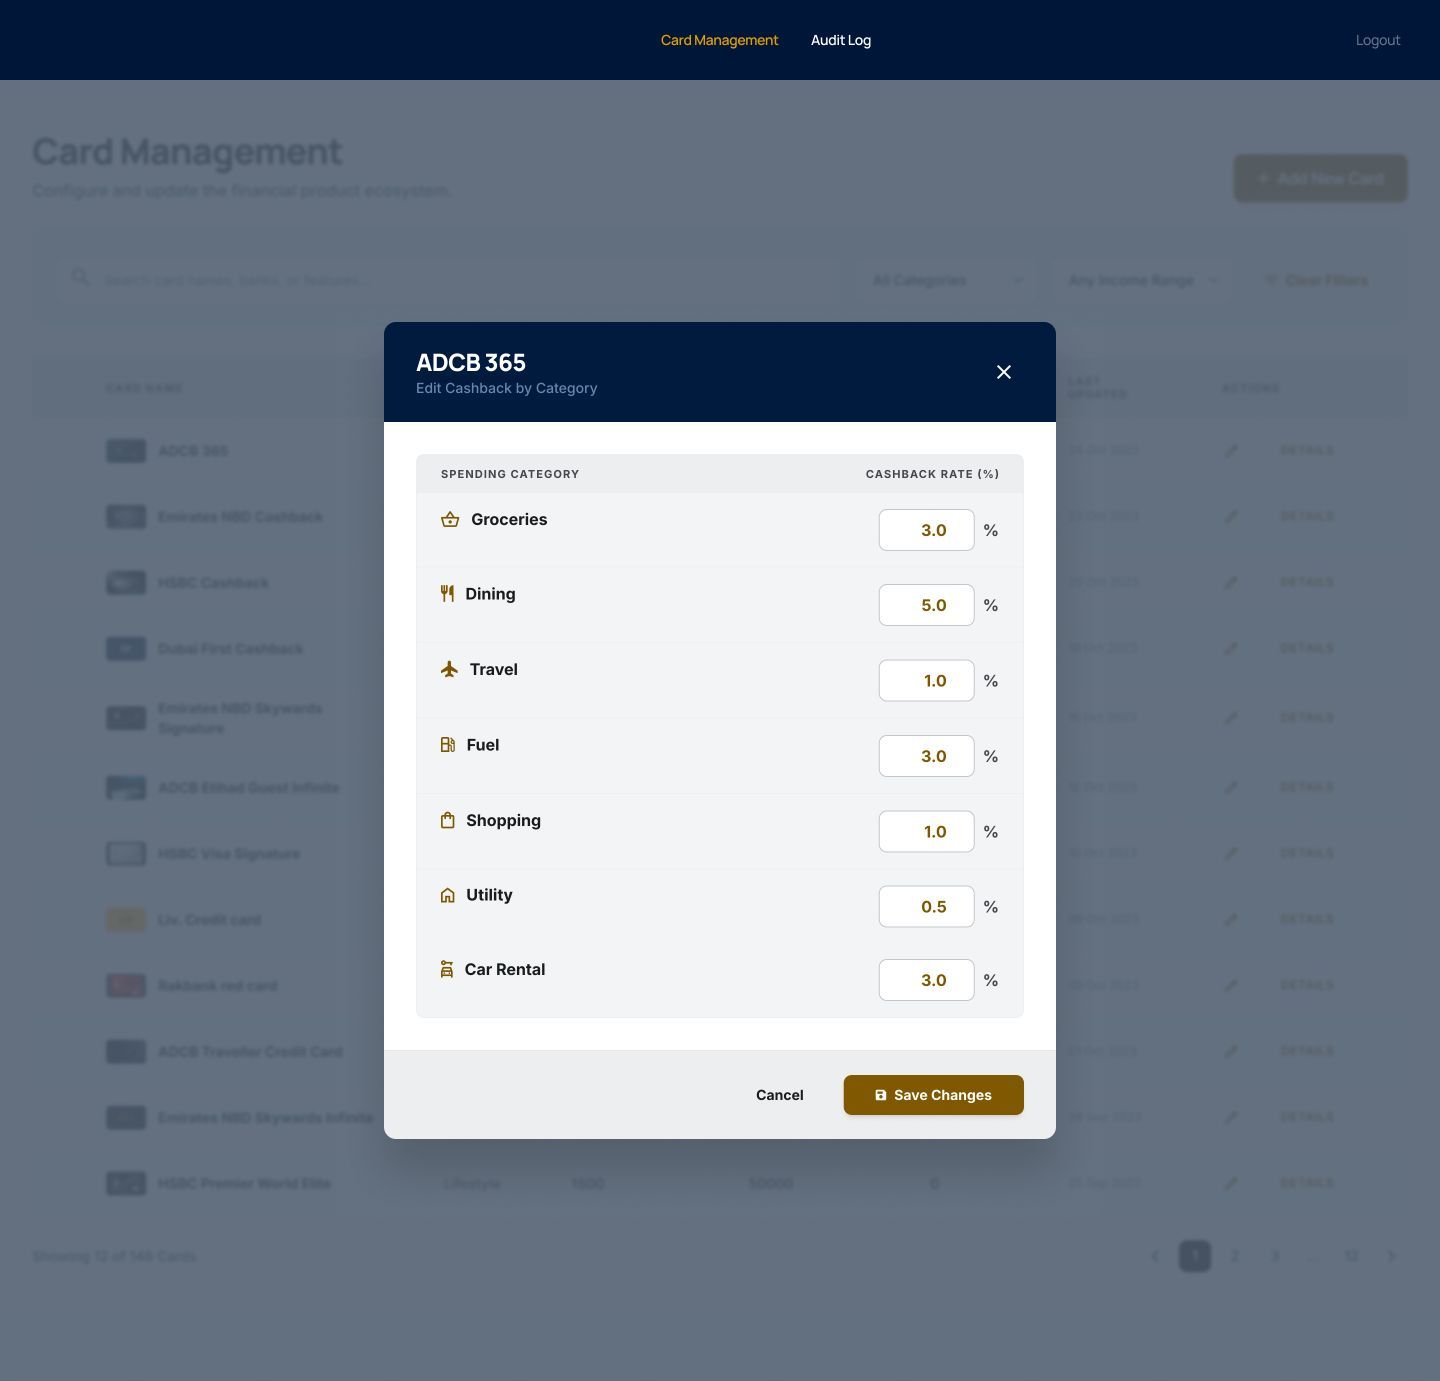
Cashback is edited per spending category, the same categories the calculator asks about.
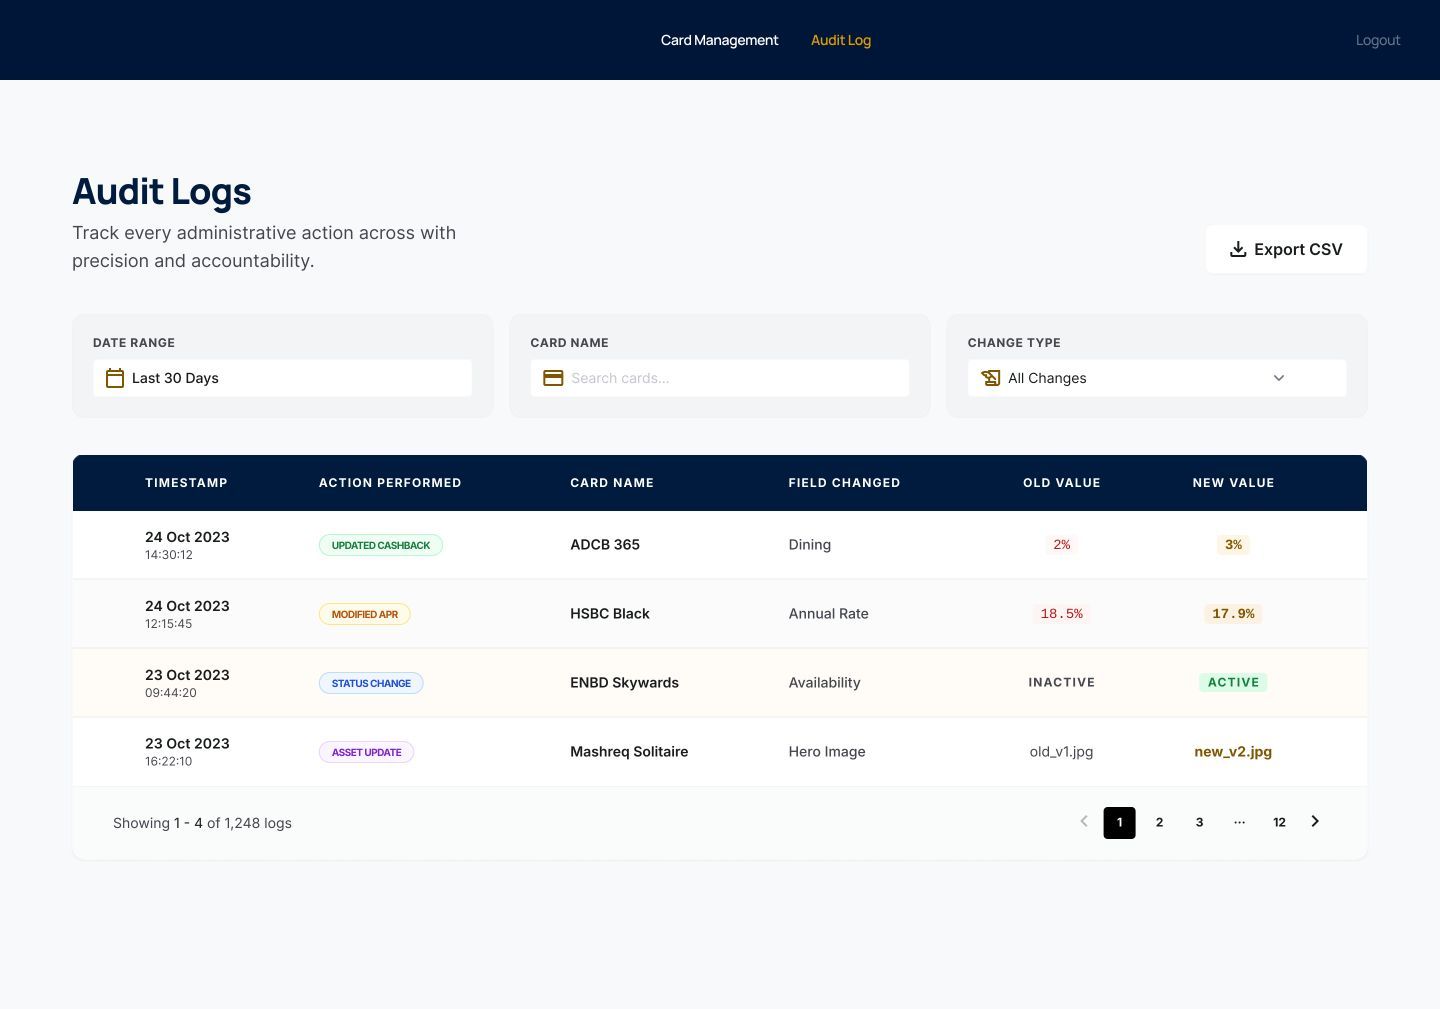
An audit log records what changed on which card, from what value to what value.
How it was built
Four stages, a founder in the room
The platform was delivered on NeoCrew. For a founder-led product that meant a working platform without first assembling a multi-person engineering team, and a process that kept the founder in the room for the decisions that mattered instead of waiting weeks between updates.
Discover
The problem, the users and the scope, written down as a product requirements document before anything is drawn.
Design
The calculator flow, results and admin screens, designed around the two questions a first-time visitor has.
Blueprint
Architecture signed off before a line of code exists: the rate model, the content layer and the capture step.
Build
Built and verified against the spec, then shipped as a live product, and kept running after launch.
Specialist AI agents do the drafting at every stage. Humans approve each gate before anything moves on, and the same team keeps operating the product after launch.
In the founder's words
Asked the right questions
The NeoCrew team asked the right questions from a founder's perspective, and that built my trust early. They weren't just interested in building the product, they were committed to helping me navigate the startup journey. The roadmap from my concept to reality has been seamless.
The outcome
Shipped. And still shipping.
The platform shipped as a live, user-facing product without a traditional in-house engineering build, and it has kept shipping since launch. Improvements like the WhatsApp-first capture flow arrive as iterations rather than as a second project, with no re-engagement and no new vendor search.
In a category where trust depends on the fine print being current and the experience feeling instant, that combination, a fast first build and a delivery partner that keeps operating the product afterward, lets the founder's small team focus on growth and content instead of on maintaining infrastructure.
What it's made of
The moving parts
Questions
UAE credit card matchmaker, answered
Who was the client?
A founder-led consumer fintech startup in the United Arab Emirates. The founder wanted a trustworthy way for residents to find the right credit card, in front of real users fast.
What is the product?
A UAE-focused credit card comparison and recommendation platform. Visitors enter their income and how they spend, and get back the cards that suit them best, ranked by estimated net annual savings after fees.
Do visitors need an account?
No. There is no login anywhere in the visitor's path. The only capture step comes after someone has seen their matches, when they choose to have their top three sent to WhatsApp.
Why WhatsApp instead of email?
Because it is the channel UAE residents already default to. An email with card results may never be opened; a WhatsApp message is. The WhatsApp flow replaced an earlier Apply Now flow after launch.
How does the platform keep card data current?
Through a purpose-built admin, not a spreadsheet. The team edits each bank's cashback categories, fees, salary thresholds and offers as they change, and a content layer handles the site's buyer-question and comparison pages without code changes.
How was the platform built?
On NeoCrew, through four stages: Discover, Design, Blueprint and Build. Specialist AI agents did the drafting and human checkpoints decided what shipped. The same team keeps operating the product and shipping improvements after launch.
Keep reading
More built on NeoCrew
AI wardrobe stylist
An AI-native styling app that reads your wardrobe from photos and restyles looks on a model matched to your body type.
Read the case study
Predictive fishing intelligence
An offline-first AI copilot that tells trawler captains where the fish will feed tomorrow. Brief to client-ready in under two weeks.
Read the case studyYour turn
Got a market that is too messy to compare?
Tell us what you are building. NeoCrew turns the idea into a product requirements document in one business day, free.